2027 Salary Budgets & Canada Work Permit Changes | October 2026 Insider

In Case You Missed It:
Mobility continues to evolve alongside shifting market conditions and global trends. Catch up on our latest insights on Canadian visa requirements, European assignments, and container shipping costs.
- Canada Work Visa Requirements for Employers: A Complete Guide
- Spotlight on Schengen: Benefits of Free Movement for European Assignments
- Employee Relocation Delays Due to Rising Container Shipping Costs
Feature Stories
Salary Budgets by Country: 2027 Projections for Global Mobility Planning
PR Newswire reports from The Conference Board’s annual survey that U.S. employers are budgeting a median 3.5% salary increase for 2027, consistent with 2026. With so little extra room in budgets, employers are steering raises toward performance, critical roles, and in-demand skills. WorldatWork’s survey of 24 countries shows a similar pattern globally.
Key points for relocation and global mobility:
- Hiring for skills will drive moves: 37.8% of employers say AI and machine-learning skills are driving base-pay increases, the most of any skill category. Recruiting that talent often means relocating it, so relocation support becomes part of the competitive offer.
- Industry differences: Projected raises range from 3.7% in technology and telecom to about 3.0% in retail and the public sector. That’s useful context for benchmarking relocation packages by industry.
- Workforce changes mean moves: 31% of employers expect headcount to grow in 2027 and only 9% expect cuts. Employers are also restructuring and automating, which tends to create internal transfers and new-hire relocations.
- Country figures for 2027: Canada is projected at 3.5% and India at 9.2%, the highest in the survey. Mexico is at 5.0% and the U.K. at 3.7%. These help clients set expectations for assignee pay in common host countries.
The Impact: With salary budgets flat, accurate assignment pay matters more than ever. CapRelo’s global compensation services help clients project assignment costs, update balance sheets with current COLA and exchange rates, and reconcile home and host payroll monthly, so our clients’ 2027 packages stay competitive and year-end reporting stays clean.
Canada Work Visa Sponsorship: New Employer Rules for LMIA Applications
Employment and Social Development Canada (ESDC) has clarified which entities qualify as the employer for Labour Market Impact Assessment (LMIA) purposes, the labor market approval many foreign worker permits require. Effective September 18, 2026, the employer must be the entity that hires, directs, and pays the worker, and staffing or employment agencies that place workers with other businesses no longer qualify. In practice, this closes off the employer of record (EOR) model for LMIA-based work permits in Canada.
Key points for relocation and global mobility:
- The EOR model is closed for LMIA: This is a significant change for companies that have relied on EORs to place workers in Canada. Clients that use EORs to place workers in Canada without a local entity need to rethink their approach.
- A risk for international transfers: If the foreign sending company maintains direct employment of the worker while they’re in Canada, the Canadian entity may not count as the employer. That matters directly for assignment structures and split-payroll setups.
- The narrower scope: The restriction applies only to LMIA applications. EORs can still operate in other arrangements under provincial employment law.
The Impact: With EORs off the table for LMIA-based permits, clients without a Canadian entity should rethink how they bring talent into Canada, and all clients should confirm that the employer named on each LMIA is the one that truly hires, directs, and pays the worker.
After Busy Season: Fall Brings More Housing Price Cuts and Few Contracts
As busy season winds down and the fall market gets underway, higher mortgage rates are pushing more sellers to cut prices while fewer buyers move forward with a purchase, according to Realtor.com’s September Housing Report, shared via PR Newswire. In September, 20.8% of listings had a price reduction, the highest September reading since 2018.
Key points for relocation and global mobility:
- Fall brings fewer contracts: New listings slipped 0.7% from a year ago as the usual seasonal flow of new homes slowed. Homes under contract fell 4.1%, the steepest annual drop since March 2025. For transferees selling this fall, that can mean fewer active buyers and longer marketing times.
- Buyers are gaining leverage: The national median list price fell to $419,250, down 1.4% from a year ago, the 11th straight month of annual declines. Higher rates, however, limit how much of that leverage buyers can use, including transferees buying at their new location.
- Regions differ sharply: Price cuts are most common in the West (22.8% of listings) and least common in the Northeast (15.2%). Salt Lake City, Denver and Portland led the major metros. Departure and destination markets matter more for estimating move costs.
- Sellers are staying in: About 5.6% of listings were pulled from the market, in line with last year. Unlike last year, sellers haven’t pulled homes off the market in large numbers this late summer and early fall; they’re cutting prices instead. That’s useful context for clients weighing BVO or guaranteed buyout programs.
The Impact: As the market heads deeper into fall, slower sales and the highest September share of price cuts since 2018 raise the risk of extended duplicate housing for transferees who own homes. CapRelo helps keep sales moving by setting fair market values and list prices up front, tracking showings and buyer feedback through Companion® to make fast pricing adjustments, and weighing every offer on more than price alone, including contingencies, financing and closing dates.
Global Radar
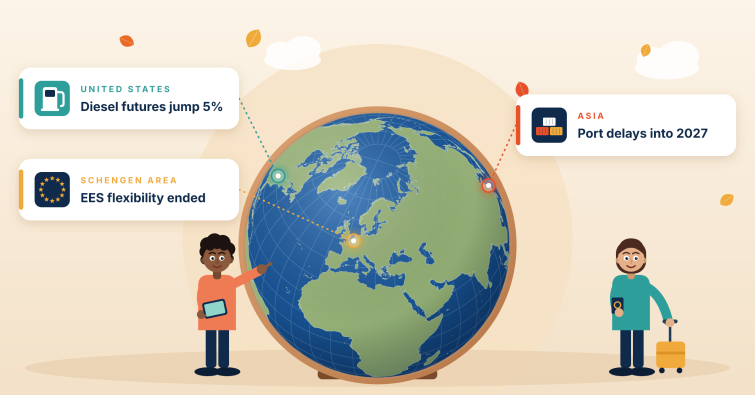 CapRelo’s Mobility Radar provides valuable insights into trends worth monitoring. This month, we have detected important global mobility updates in Asia, the Schengen Area, and the U.S.
- Record container volumes out of China, typhoon backlogs, and Golden Week sailing cancellations could keep Asia’s ports congested through summer 2027. Freight forwarder Dimerco expects the Port of Shanghai to stay severely congested into mid-to-late October, with berthing waits of more than five days and waits over nine days at one terminal.
- The temporary flexibility that let Schengen border officers scale back EES biometric checks expired on Sept. 6, so travelers may face longer waits at busy crossings. ETIAS now looks likely to slip to 2027; no applications are being accepted yet, and any site offering ETIAS applications is not legitimate.
- U.S. diesel futures jumped 5% on Oct. 13 to their highest level in weeks, as markets doubted that recent federal efforts to boost supply would bring meaningful price relief. For domestic household goods shipments, fuel surcharges are already running up to 29% of linehaul (transportation) costs. Analysts warn the $6.53 retail record could be broken later this fall, which would push surcharges even higher.


