Lump Sum Relocation Packages: A 2026 Guide for HR Mobility Leaders

A lump sum relocation package is a one-time payment an employer gives a transferee to cover the costs of moving for a new role, which the transferee then spends as they see fit. It’s one of the most common forms of relocation assistance because it’s simple to run and easy to budget.
Simple isn’t the same as easy, though. The amount, the tax treatment, and the support around it decide whether a lump sum helps you win and keep talent, or leaves a transferee managing a home sale alone. If you want a ready-made framework, start with CapRelo’s free Lump Sum Relocation Guide & Checklist for HR Leaders.
This guide covers:
- What a lump sum relocation package is and what it covers
- How packages are paid and taxed in 2026
- The four main types, and how they compare to managed programs
- How to build a lump sum relocation policy that holds up
What Is a Lump Sum Relocation Package?
A lump sum relocation package is a fixed financial allowance paid to a transferee to cover relocation costs. The transferee decides how to spend it, and usually doesn’t need to submit receipts.
For employers, the appeal is predictability: one number per move, set in advance. For transferees, it’s control. A renter moving across the state and a family selling a home across the country can each spend the money where they need it most.
What Expenses Does a Lump Sum Relocation Package Cover?
A lump sum is meant to cover the core costs of a move, typically:
- Household goods shipment, including packing and storage
- Travel to the new location for the transferee and family
- Temporary housing while they find a permanent home
- House-hunting trips
- Home sale closing costs or lease termination fees
- Vehicle shipment
- Miscellaneous costs such as utility hookups and licensing
Because transferees control the funds, a renter might put most of it toward temporary housing, while a homeowner puts it toward closing costs. For typical amounts by employee level, see our guide to relocation package costs and benchmarks.
How Are Lump Sum Relocation Payments Made?
There are three common ways to deliver relocation funds. Only the first is a true lump sum, but many policies combine them.
1. Cash Lump Sum Payment
The employer pays a set amount directly to the transferee, usually through payroll. The transferee manages every moving cost on their own. The payment is taxable income, so unless the employer provides a relocation tax gross-up, the transferee absorbs the full tax bill.
2. Direct Payment to Suppliers
The employer pays suppliers directly and is billed for the services. The transferee handles less paperwork, and the employer gets more control over cost and quality.
3. Expense Reimbursement
The transferee pays costs up front and submits receipts for reimbursement after the move. It’s more flexible than direct billing, but it asks the transferee to carry the costs for weeks. For a side-by-side comparison, read Relocation Reimbursement vs. Bonus Explained.
Are Lump Sum Relocation Packages Taxable?
Yes. Lump sum relocation payments are taxable wages for federal income and payroll tax purposes. The 2017 Tax Cuts and Jobs Act suspended the moving-expense exclusion through 2025, and the One Big Beautiful Bill Act, signed in July 2025, made that repeal permanent. Active-duty military moves remain the main exception.
That means a $10,000 lump sum can leave a transferee with far less to spend, depending on their tax bracket. Many employers offer a tax gross-up to close that gap, and budget for it up front.
The Four Types of Lump Sum Relocation Packages
1. Flat (Fixed) Lump Sum
Every eligible transferee receives the same amount, regardless of level or situation. It’s the simplest to run, and works best for high-volume, early-career moves where costs are similar.
2. Variable Lump Sum
The amount is set by criteria the employer defines, such as move distance, homeowner or renter status, family size, and job level. It’s fairer than a flat amount, but needs clear tiers to stay consistent.
3. Partial Lump Sum
The employer covers some costs with a lump sum and pays or reimburses others directly. Household goods shipment and the final move are the most common items kept out of the lump sum, because they’re the costliest and hardest for a transferee to price.
4. Managed Lump Sum
The transferee receives a capped amount under a written policy that defines what it covers, limits, and receipt rules. A relocation management company (RMC) guides the transferee on how to spend it, so they get the lump sum’s flexibility without navigating the move alone. To set one up, work through our step-by-step lump sum relocation checklist.
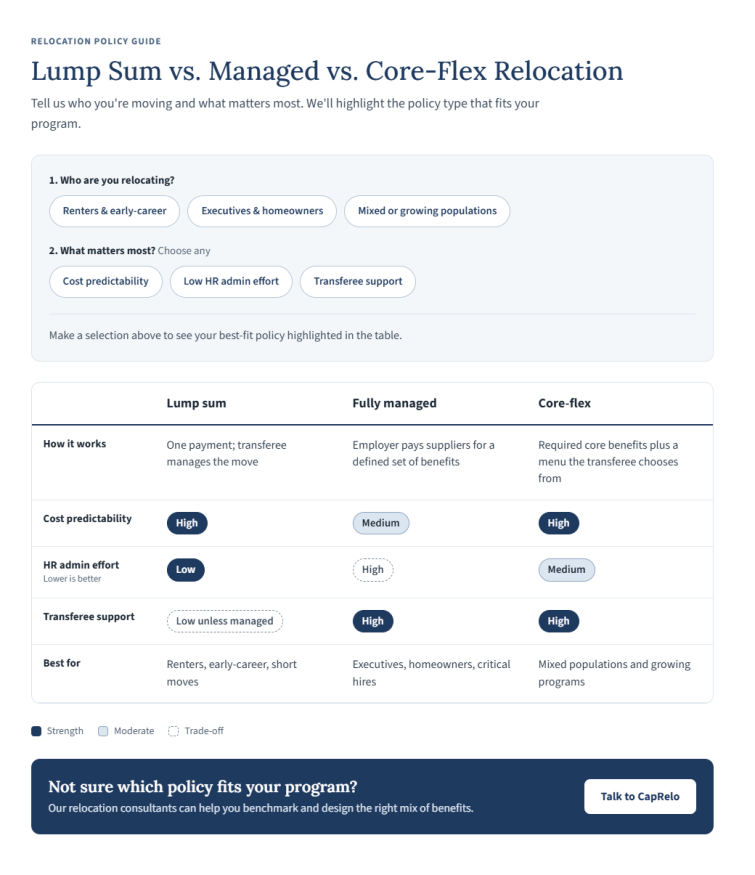
Many mobility teams land on core-flex as the middle path. With CompanionFlex, transferees choose the benefits that fit their move from a set budget, while HR keeps policy and cost control.
How to Negotiate a Lump Sum Relocation Package
Set expectations early, and in writing. Ask the transferee for a rough timeline and the parts of the move that drive cost, such as a home sale, school-age children, or vehicles. Come to the conversation knowing your tier amounts, whether a gross-up applies, the start date, and what support your RMC provides. A clear package with defined support is easier to accept than a larger number with none.
What Are Other Companies Offering?
Lump sums are no longer just for entry-level hires. According to the Atlas Corporate Relocation Survey, companies are about equally likely to offer lump sums to experienced professionals (59%), executives (55%), and entry-level employees (50%).
Partial lump sums tend to use one fixed amount across levels. Lump-sum-only policies more often vary by level or need, with homeowner vs. renter status and move distance weighing most.
The Trade-offs of Lump Sum Relocation Packages
Where Lump Sums Save Money
 Lump sums lower upfront costs and cut administration. HR doesn’t need to track line items for temporary housing, house hunting, the final move, home sale help, and lease breaks. The short-run advantages:
- Lower and more predictable upfront cost
- Less administrative work for HR mobility teams
- More flexibility for transferees
- Faster approvals and fewer exceptions
The Hidden Costs
The biggest risk is the transferee experience. With a bare lump sum, a homeowner may be left to sell one home and buy another on their own. That’s a heavy load that can hurt productivity in the new role and erode goodwill, especially for transferees used to more structured programs.
Lump sums can also run short when the tax hit isn’t planned for, which leads to exception requests that erase the savings. A well-designed, well-managed policy matters more to retention than the package type. CapRelo’s free Lump Sum Relocation Guide for HR Leaders is a practical starting point.
How to Build a Lump Sum Relocation Policy
A strong policy answers five questions before the first offer goes out:
- Eligibility. Which roles, levels, and move distances qualify?
- Amounts. Is it flat or tiered, and by what criteria?
- Coverage. What is the lump sum meant to cover, and what’s paid directly?
- Tax treatment. Will you gross up, and is that budgeted?
- Support. Who does the transferee call when they need help?
Our lump sum relocation policy template and checklist walks through each step, with pitfalls to avoid and best practices from 25+ years of managing relocations.
Lump Sum Relocation Packages: Key Takeaways
Lump sum packages offer flexibility, cost predictability, and less administration. They work best with clear tiers, a planned tax approach, and real support for the transferee.
Download the free guide or talk to a CapRelo mobility expert about the right structure for your workforce.
Frequently Asked Questions (FAQs)
What is a typical lump sum relocation package?
It varies by employee level, homeowner or renter status, and move distance. Entry-level and renter packages often fall in the low-to-mid thousands, while homeowner and executive packages run much higher. See CapRelo’s guide to relocation package costs for benchmarks by tier.
Is a lump sum relocation package taxable?
Yes. Lump sum relocation payments are taxable wages. The One Big Beautiful Bill Act of 2025 permanently ended the federal moving-expense exclusion for most employees, so transferees owe income and payroll tax on the full amount unless the employer provides a tax gross-up.
What are the pros and cons of a lump sum relocation package?
Pros: easy to administer, flexible for transferees, and predictable for budgets. Cons: without guidance, transferees, especially homeowners, may manage a stressful and expensive process alone, which can hurt satisfaction and retention.
How is a lump sum relocation amount calculated?
Most companies weigh move distance, job level, homeowner or renter status, and family size. Variable programs score each factor, while fixed programs set one amount per tier. Benchmarking against current market data keeps amounts competitive.
What is the difference between a lump sum and a managed relocation?
A lump sum gives the transferee cash to manage their own move. A managed relocation has the employer, usually through an RMC, pay suppliers directly for defined benefits. Managed lump sums and core-flex programs combine the two.
How do I create a lump sum relocation policy?
Define eligibility, set tiered amounts, list what the lump sum covers, decide on tax gross-up, and name the support transferees will get. CapRelo’s free Lump Sum Relocation Guide & Checklist for HR Leaders walks through each step.


